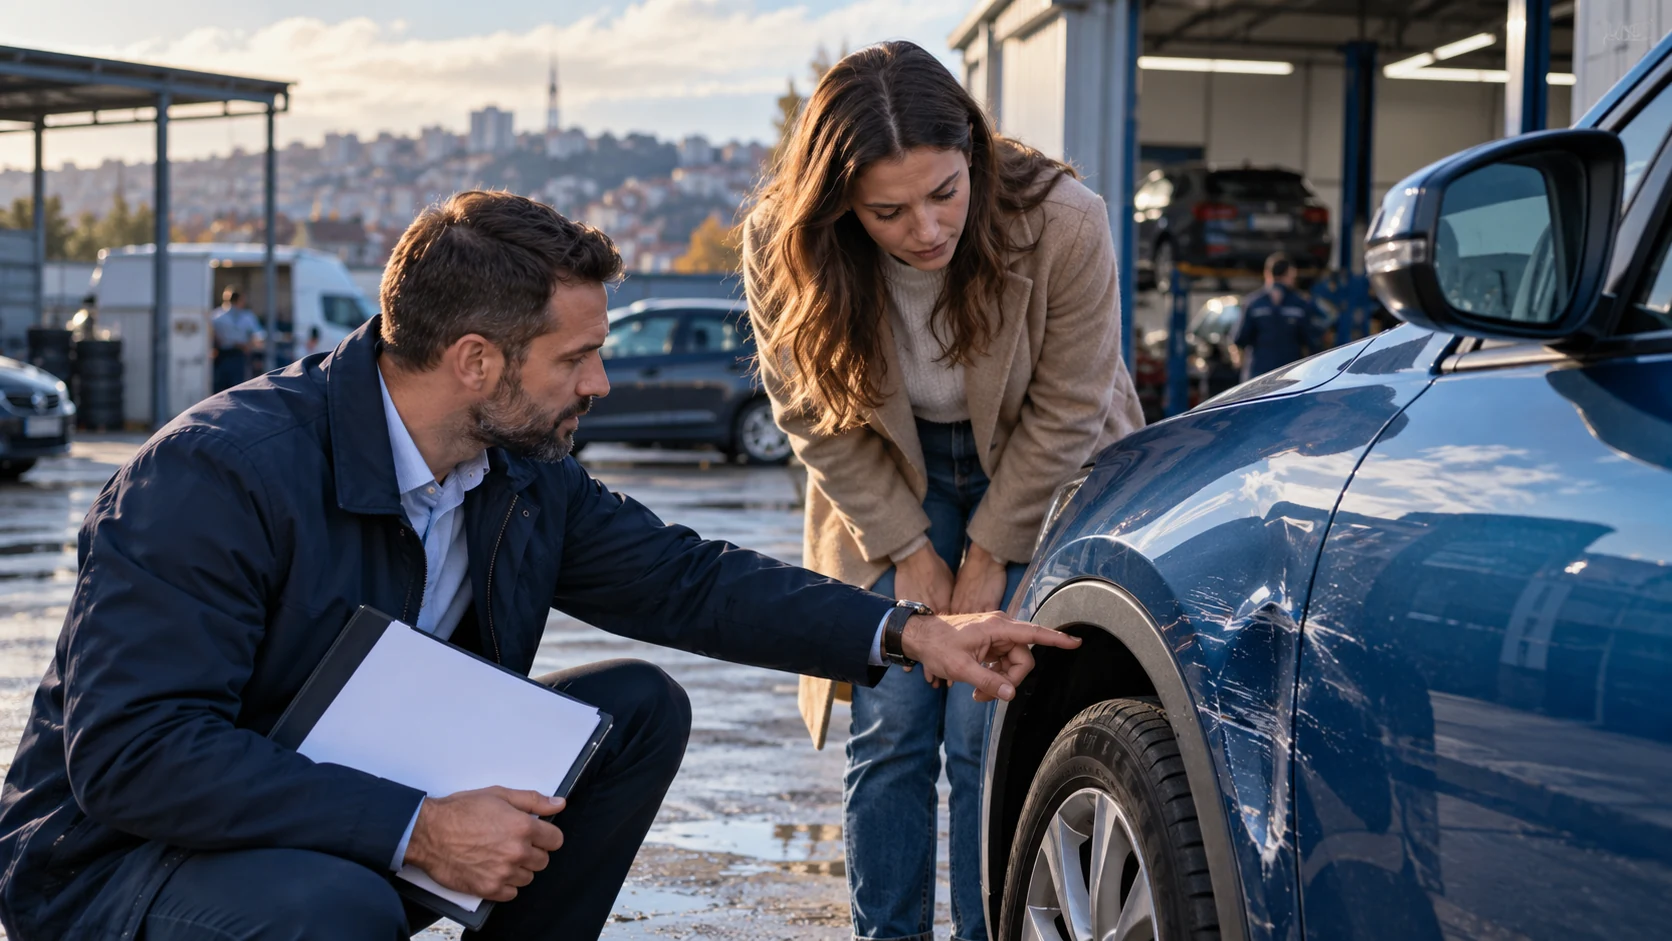
In short
Third-party liability is compulsory insurance for liability for damage caused to third parties by using a vehicle. Comprehensive insurance is voluntary cover for your own vehicle against agreed risks, with exclusions, an excess and other conditions set out in the policy.
Who third-party liability protects
Third-party liability insurance relates to the vehicle holder's liability for damage caused to third parties. Its purpose is not to automatically pay for every bit of damage to the policyholder's own car.
That is why the sentence 'I have insurance' is not precise enough. In an accident, what matters is who is liable, who suffered the damage and which event is covered.
What comprehensive insurance adds
Comprehensive insurance is taken out voluntarily to protect your own vehicle against chosen risks. The scope can be wider or narrower, so two policies with the same name do not necessarily offer the same cover.
Check the risks, territorial validity, deductible or excess, valuation method and exclusions. Ask specifically about theft, glass, parking damage, natural disasters and what happens when the driver causes the damage.
Partial cover only makes sense if you know what was chosen
Partial comprehensive cover can apply to specific risks or parts of the vehicle, such as glass, depending on the product terms. A lower price is no benefit if you expect wider cover that was not agreed.
Ask for a written overview of what is and is not included. A verbal summary is useful, but the policy terms take precedence.
Questions before you sign
Ask what your share of a claim is, how the vehicle's value is determined, whether there are special protection requirements, where the policy is valid and whom you contact first when something happens.
AC Bugarski can help you compare the basic options, but make the final decision only once you have read the insurer's document.
- which risks are covered
- what the exclusions are
- how much the deductible or excess is
- how and by when a claim is reported
Key points
Three things to remember
- 01
Third-party liability and comprehensive insurance do not cover the same property or the same risks.
- 02
A package name is not enough; read the cover, exclusions and excess.
- 03
Report damage as the policy instructs and keep the paperwork.
FAQ
Straight answers
Does third-party liability pay for repairs to my vehicle?
Not automatically. It covers liability for damage caused to third parties. Compensation for damage to your vehicle depends on the other party's liability or on agreed comprehensive cover.
Does comprehensive insurance cover all damage?
No. It covers the agreed risks under the policy terms, with listed exclusions and a possible excess paid by the insured.
Is the cheapest policy the best?
Price is only one criterion. Compare the scope of cover, exclusions, excess, the claims procedure and the quality of service when damage occurs.
Sources and further reading
This article is informational. Check regulations, conditions and changing figures before a specific procedure.